Quick Summary
The best payment processor for a small business depends on whether you sell in person, online, or both, and on your total monthly cost rather than the advertised rate. Local Credit Card Processing suits in-person retail and service businesses that want free equipment and local tech support, while Square and Stripe fit very small sellers and online sellers respectively. Compare every provider using your own transaction mix.
- Your effective rate is total processing cost divided by total card volume, and it shifts with your transaction mix.
- Monthly minimums, batch fees and equipment leases can make a low headline rate cost more overall.
- Ask each provider for an itemized monthly estimate based on your real volume before you compare.
- A free terminal may be recovered through a higher processing rate, a monthly fee or a multi-year contract.
- Get reserve terms, payout hold triggers and early termination costs in writing before you sign.
Table of Contents
- How Payment Processing Works for a Small Business
- How We Tested and Evaluated Payment Processor Reviews
- Best Online Payment Processor for Small Business: Provider Reviews
- Small Business Payment Processing Fees Compared by Transaction Mix
- Mobile Payment Options for Small Business
- Free Credit Card Processing for Small Business: What the Offer Really Costs
- Contract, Reserve and Account-Freeze Risks to Check Before You Sign
- Choosing Your Payment Processor and Booking a Local Quote
- Frequently Asked Questions
How Payment Processing Works for a Small Business
Payment processing is the system that moves a customer’s card payment from your register to your bank account. A single sale can involve four parties: the customer, your merchant account, the card network, and the customer’s bank.
Most small businesses never see the full breakdown. The fee you pay is usually a combination of interchange (set by the card networks and issuing banks), network assessments, and the processor’s markup.
Three things drive what you pay:
- Card type: Rewards and corporate cards cost more to accept than basic debit cards.
- Entry method: A chip or tap transaction typically costs less than a manually keyed one.
- Transaction timing: Batches that close late or get delayed can trigger higher rates.
How We Tested and Evaluated Payment Processor Reviews
This guide compares processors on the criteria that matter most to a small business owner: total cost, contract terms, hardware options, and support availability. Where we describe a provider’s features or pricing, we draw on published provider materials and the research available to us, and we flag where details are unverified.
We grade each provider on five points:
- Total cost at your volume. We model monthly cost for a small retail or service business rather than relying on advertised rates alone.
- Contract and exit terms. Early termination fees and equipment leases can cost more than a higher processing rate.
- Hardware and integration. We check whether the terminals and point-of-sale tools fit a typical small operation.
- Support hours. We note whether help is available outside business hours.
- Transparency. Clear fee disclosure earns a higher score than pricing that requires a call to decode.
Scores reflect the quality of available information. Where a provider does not publish a figure, we say so instead of estimating.
Best Online Payment Processor for Small Business: Provider Reviews
Choosing the best online payment processor depends on whether you sell online, in person, or both. Local Credit Card Processing offers free equipment and dedicated local tech support for small businesses that want a single provider for in-person and card-present payments.
Here is how the main options compare at a glance:
| Provider | Best For | Equipment | Support | Pricing Visibility |
|---|---|---|---|---|
| Local Credit Card Processing | In-person retail and service businesses | Free equipment offered | Local tech support, 24/7 customer support | Transparent pricing page |
| Square | Very small sellers, quick setup | Sold or leased hardware | Online and phone support | Published flat rates |
| Stripe | Online sellers and developers | Software-first, hardware optional | Documentation and email support | Published per-transaction rates |
Pros and cons of each provider
Local Credit Card Processing
- Pros: Free equipment, dedicated local tech support, 24/7 customer support, easy integration.
- Cons: Full pricing details sit on the provider’s pricing page, so you will need to request a quote before comparing totals.
Square
- Pros: Fast setup, widely recognized hardware, simple published rates.
- Cons: Hardware costs can add up across multiple terminals, and support is largely self-serve.
Stripe
- Pros: Strong online checkout tools and developer flexibility.
- Cons: Less suited to in-person retail, and setup can require more technical work.
Watch out: Compare providers using the same transaction mix. A low advertised rate means little if the monthly fee or equipment lease makes the total higher.
Small Business Payment Processing Fees Compared by Transaction Mix
Headline rates tell you almost nothing about what you will actually pay. The number that matters is your effective rate, total processing cost divided by total card volume, and it moves with your transaction mix. Two businesses with identical monthly volume can pay very different totals depending on average ticket size, the share of card-present versus online sales, and how often cards are keyed in manually.
Fee structures generally fall into two models:
- Flat-rate pricing: One percentage plus a per-transaction fee on every sale. Easy to predict, but you overpay on debit and basic cards because the flat rate bundles in a markup well above the underlying card cost.
- Interchange-plus pricing: The actual interchange and network cost passed through at cost, plus a fixed markup and often a monthly fee. Usually cheaper at higher volume, but the statement is harder to read without help. For a side-by-side explanation of how each model works and which saves money, see flat fee vs interchange plus processing fees.
Worked cost scenarios
To compare processors on equal terms, model your own volume rather than trusting an advertised percentage. The three scenarios below use commonly published rate structures and typical card-mix assumptions; plug in your own statement figures to replace them. All amounts are in USD.
The fee lines that inflate the total
Beyond the rate, these charges change the math and are easy to miss on a statement:
-
Monthly minimums: If you fall short of a set processing volume, you pay the difference. Seasonal businesses feel this most.
-
Batch fees: A small charge each time you settle, which adds up for businesses that batch daily.
-
Chargeback fees: Charged per disputed transaction, plus the risk of a rolling reserve if disputes spike.
-
Equipment leases: A terminal lease can cost more over time than buying the hardware outright.
Watch out: A processor quoting a low percentage but charging a monthly minimum, a statement fee, and a batch fee can cost more in total than a higher headline rate with none of those lines. To see each of these charges explained and how to negotiate them, read the hidden credit card processing fees most small businesses miss. (Source: PCI Security Standards Council guidelines)
Mobile Payment Options for Small Business
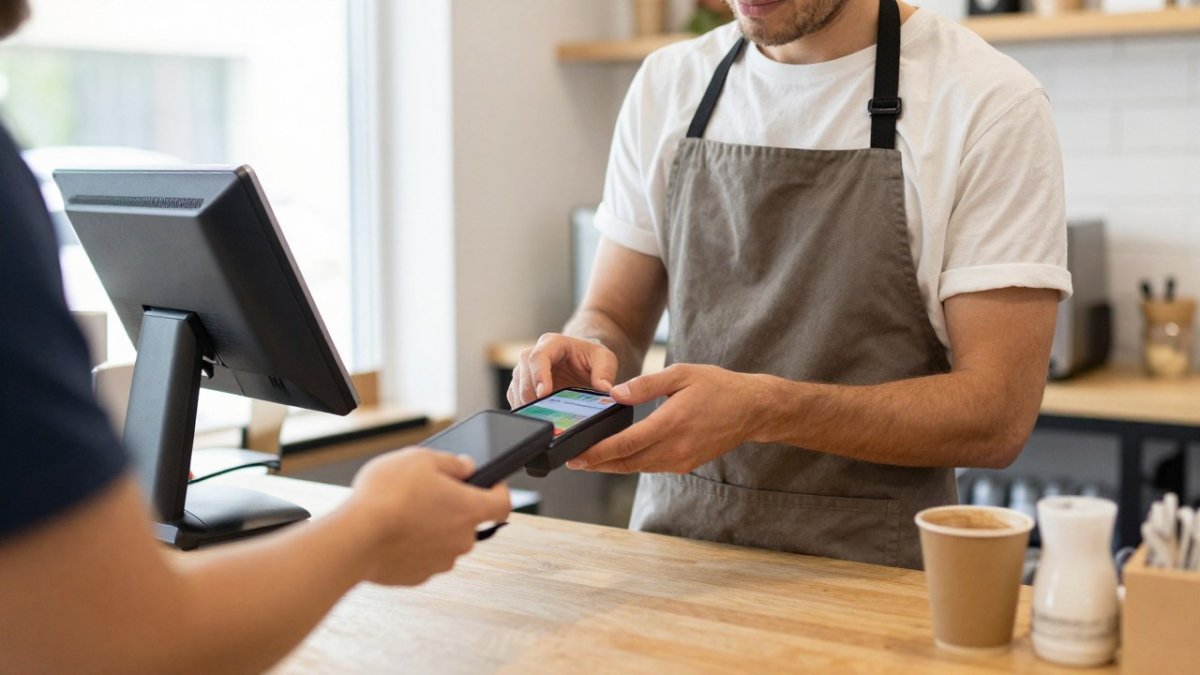
Mobile card readers let you accept payments at a market stall, on a service call, or at a table in a dining room. A café owner tapping a contactless reader at the counter while a customer holds up a phone shows how quickly these tools fit into a busy shop.
When evaluating mobile options, check:
- Whether the reader works offline and syncs later
- Battery life and charging method
- Whether it accepts digital wallets and contactless cards
Free Credit Card Processing for Small Business: What the Offer Really Costs
“Free” terminal offers are common, but they rarely come without trade-offs. The equipment cost may be recovered through a higher processing rate, a monthly fee, or a multi-year contract.
Before accepting a free terminal, ask:
- What is the effective rate once the equipment is factored in?
- Is there a monthly minimum or statement fee?
- What happens to the terminal if you cancel early?
Local Credit Card Processing advertises free equipment with no upfront equipment costs. Confirm the full terms in writing, including any processing rate or contract length tied to the offer. You can learn more about the free credit card terminal options available before deciding.
Contract, Reserve and Account-Freeze Risks to Check Before You Sign
Contract terms can cost more than any rate line, and they are the part of a processing agreement most owners skim. The risks below affect your cash flow directly, so read the termination, reserve, and hold sections of any agreement before you sign, not after your first deposit is delayed.
Early termination fees
An early termination fee is a penalty for leaving before your contract term ends. It is usually calculated one of three ways:
- Flat fee: A set amount stated in the agreement.
- Remaining months times a monthly minimum: For example, a $25 monthly minimum with 18 months left equals a $450 exit cost.
- Remaining processing volume times a rate: Some agreements charge a percentage of the volume you would have processed. This is the most expensive version and the hardest to predict.
Equipment leases are separate from processing contracts. A lease can run for several years, and canceling early may require paying the remaining lease balance even if you stop processing. Ask whether the terminal is sold, leased, or provided free with a processing commitment, and get the answer in writing.
Rolling reserves
A rolling reserve is a percentage of your sales that the processor holds back for a set period to cover chargeback risk. The reserve percentage and holding period are set in your agreement. Reserves are most common for businesses with elevated chargeback exposure, such as subscription, travel, and high-ticket sellers, but they can be applied to any account the processor considers higher risk.
Payout holds and account reviews
A payout hold is a temporary freeze on deposits, often triggered by a spike in volume, a jump in chargebacks, a change in your business model, or activity the processor’s risk system flags as unusual. Holds can last days or weeks, and during that time you are still delivering goods or services. Ask every provider these questions before signing:
- What specific triggers cause a hold or account review?
- How long do holds typically last, and who can release them?
- What documentation will you require to resolve a review?
- Will you notify me before freezing deposits, or only after?
Underwriting and account approval
Underwriting is the processor’s review of your business before approval, your entity type, industry, expected volume, and chargeback history. Some industries are classified as high-risk and face higher rates, reserves, or outright declines.
Watch out: A provider that will not put reserve terms, hold triggers, and termination costs in writing before you sign is telling you something about how it will treat you after.
Before you commit, compare these terms across at least two providers and ask for a sample statement at your real volume so the total cost, including any reserve, is visible up front. You can also review how PCI compliance is handled for local card processing before signing.
Choosing Your Payment Processor and Booking a Local Quote
Start by listing your monthly card volume, average ticket size, and whether you sell in person, online, or both. Use those numbers to request an itemized quote from each provider.
If you run a small retail, food, or service business and want a processor with free equipment, local tech support, and transparent pricing, you can request a quote from Local Credit Card Processing.
Need more detail on pricing before you decide? Read our guide to flat-fee versus interchange-plus processing, then compare the full cost against your current statement.
Frequently Asked Questions
What is the best payment processor for a small business?
The best payment processor depends on how you take payments. Businesses that sell mostly in person need a reliable card reader and fast deposits, while online sellers need a gateway that handles checkout, recurring billing and fraud screening. Compare the per-transaction rate, monthly fees, hardware costs and contract length for your own monthly sales volume rather than relying on the headline rate. Local Credit Card Processing offers free equipment, system integration and local tech support; check its pricing page for current rates and request a quote for your specific setup.
How much do payment processors charge small businesses?
Costs usually combine a percentage of each sale plus a fixed per-transaction fee, and may include monthly fees, setup fees, chargeback fees and hardware charges. Pricing models such as flat-rate and interchange-plus can produce very different totals for the same sales. Estimate your monthly card volume and average ticket size, then compare total cost across providers over a year. Local Credit Card Processing publishes its pricing on its website, so you can check current rates there or request a quote.
Can a small business accept credit cards without a monthly fee?
Some providers waive monthly fees but usually recover that cost through higher per-transaction rates or hardware charges. Before choosing a no-monthly-fee option, add up the total you would pay over a typical month and over a year. Check whether the offer requires a contract, an early termination fee or a minimum processing volume. Local Credit Card Processing states that its equipment is free, and you can confirm the full fee structure on its pricing page.
What is the difference between a payment processor and a merchant account?
A merchant account is the bank account that holds funds from card sales before they are paid out to your business. A payment processor moves transaction data between your point-of-sale system or checkout page and the card networks and banks. Many providers bundle both, but some separate them, which can affect your fees, underwriting and how quickly you get paid. Ask any provider whether the merchant account is bundled, who owns it and what happens to your funds if the account is reviewed.

Recent Comments