Last Updated: November 4, 2026
Quick Summary
Better alternatives to popular payment processors depend on what is driving your search, such as hard-to-predict fees, outdated hardware, slow support, or lock-in contracts. Compare each option’s all-in annual cost using your own last 12 months of statements, including hardware, monthly fees, chargebacks and termination charges, not just the advertised rate.
- Add up every line on your last 12 months of processing statements and divide by card sales to get an effective rate.
- A low advertised rate with a high monthly fee can cost more than a higher rate with no monthly charge.
- Merchant accounts suit steadier, higher-volume sales; payment aggregators suit new or low-volume businesses.
- Confirm offline storage limits, amount caps and what happens if an offline transaction is later declined.
- Ask each provider for a written quote using your own volume, average ticket and card mix before deciding.
Table of Contents
- How In-Person Processing Fees Really Add Up
- Alternatives Organized by the Processor You Are Replacing
- Merchant Account vs Payment Aggregator: Which Model Fits Your Sales
- Low-Volume, Occasional and Event-Based Selling Options
- PCI DSS Compliance and Offline Mode: What to Check Before You Switch
- Your Next Step: Compare Quotes Using Your Last 12 Months of Statements
- Frequently Asked Questions
Many business owners reach a point where their card processing setup stops fitting the business. This guide explains what to compare, where the costs really sit, and how to decide whether a switch makes sense for your sales. (Source: the Federal Trade Commission’s guidance on unfair or deceptive practices)
Popular payment processors such as Square, Stripe and PayPal are easy to start with. Their self-serve signup, flat-looking rates and bundled hardware make them a sensible default. The trouble usually appears later.
The common reasons owners look elsewhere tend to fall into a few groups:
- Fees that are hard to predict. Per-transaction rates, monthly fees and add-ons make monthly totals difficult to forecast.
- Hardware that no longer fits. A single countertop reader may not suit a shop that now also sells at events or takes orders by phone.
- Support that is hard to reach. When a terminal fails during a busy lunch rush, a self-serve help page is not enough.
- Contracts and cancellation terms. Some owners discover lock-in periods or cancellation fees only after they try to leave.
Each of these problems has a different fix, so the right alternative depends on which one is driving the search. The sections below work through the costs, the processor models and the migration steps in order.
How In-Person Processing Fees Really Add Up
The headline rate is rarely the whole cost of accepting cards in person. Most owners pay several separate charges, and the total is what matters. Common components include:
- The per-transaction percentage and fixed fee
- A monthly software or platform fee
- Terminal rental or purchase costs
- Fees for extra features, such as reporting or inventory tools
- Chargeback and dispute handling fees
- Statement, batch or PCI compliance fees that appear only on the monthly bill
A simple check helps. Take the last 12 months of processing statements, add up every line, and divide by your total card sales. That gives an effective rate you can compare across providers. An effective rate often reveals a gap that the advertised rate hides.
Watch out: A low advertised rate paired with a high monthly fee can cost more than a higher rate with no monthly charge. Always compare the all-in figure, not the headline percentage.
A Realistic Total-Cost Model for In-Person Sales
To compare alternatives fairly, build one model and run every provider through it. Use a consistent example: a shop processing $20,000 per month in card sales across 1,000 transactions, for an average ticket of $20. Add hardware, monthly fees, chargebacks and contract costs, not just the rate.
| Cost line | Provider A (flat-rate aggregator) | Provider B (merchant account, interchange-plus) |
|---|---|---|
| Advertised rate | 2.6% + $0.10 | Interchange-plus, quoted as cost + 0.30% + $0.10 |
| Monthly platform fee | $0 | $25 |
| Terminal hardware | $49 one-time reader, or $0 with a monthly plan | $299 countertop terminal, purchased |
| Chargeback fee | $15 per dispute | $15-$25 per dispute |
| PCI compliance fee | $0 if using the provider’s validated terminal | $0-$99 per year, depending on the program |
| Contract | Month-to-month | 12-month term with early termination fee |
Processing cost depends on each provider’s pricing structure, card mix and volume. Request a written quote from each provider using your own figures, then compare the all-in annual cost.
Run the comparison at your own volume, average ticket and card mix before you decide.
Costs Owners Commonly Miss
- Chargebacks. A single dispute can cost $15-$25 in fees plus the reversed sale. High-risk categories see more of them.
- Hardware replacement. Readers fail, and replacement costs vary widely between providers.
- Contract termination. Some merchant accounts charge an early termination fee, often a few hundred dollars, if you leave before the term ends.
- Statement and batch fees. Small monthly charges that rarely appear in advertised pricing.
- PCI non-compliance fees. Providers may charge a monthly penalty if your yearly self-assessment questionnaire is not completed.
Add these lines to the model. A provider that looks cheapest on rate alone can lose on the all-in annual figure once hardware, chargebacks and contract costs are included.
Alternatives Organized by the Processor You Are Replacing
The best alternative depends on the platform you are leaving. A business moving off a point-of-sale bundle has different needs from one replacing a standalone card reader.
Replacing Square or Toast Terminals
Owners leaving all-in-one restaurant or retail systems often want to keep their menu, inventory and reporting while changing how cards are processed. Before switching, confirm whether your POS software can work with a different processor. Some integrations are fully supported, while others only work with the original provider’s terminals. Ask the new provider in writing which features will and will not carry over.
Replacing Stripe or PayPal Card Readers
Owners leaving card readers tied to online-first platforms often find that the hardware is the main constraint. Readers built for ecommerce checkout may not handle in-person chip and contactless payments as smoothly as dedicated terminals. Check the EMV chip, contactless and tap-to-pay support on any replacement reader, and confirm that it works with your current sales channels.
Merchant Account vs Payment Aggregator: Which Model Fits Your Sales
Two broad models dominate small-business processing, and the choice affects cost, approval speed and control.
A merchant account is a dedicated account between your business and a bank or processor. It usually offers more control over pricing and settlement, and it can suit higher and steadier sales volumes.
A payment aggregator lets you start accepting cards quickly under a shared, pooled account. Setup is faster and often simpler, which suits new or low-volume businesses.
Neither model is better in every case. A steady, higher-volume shop often benefits from a merchant account. A seasonal or new business may prefer the speed of an aggregator. Ask each provider how it handles holds, reserves and account reviews before you commit.
Low-Volume, Occasional and Event-Based Selling Options
Many businesses do not sell every day. A food truck, a craft vendor at weekend markets, or a service provider who takes payment at pop-up events has very different needs from a fixed storefront. For these sellers, monthly fees and contract minimums can outweigh the savings on each sale. This is the area mainstream processor roundups cover least, so it is worth working through carefully.
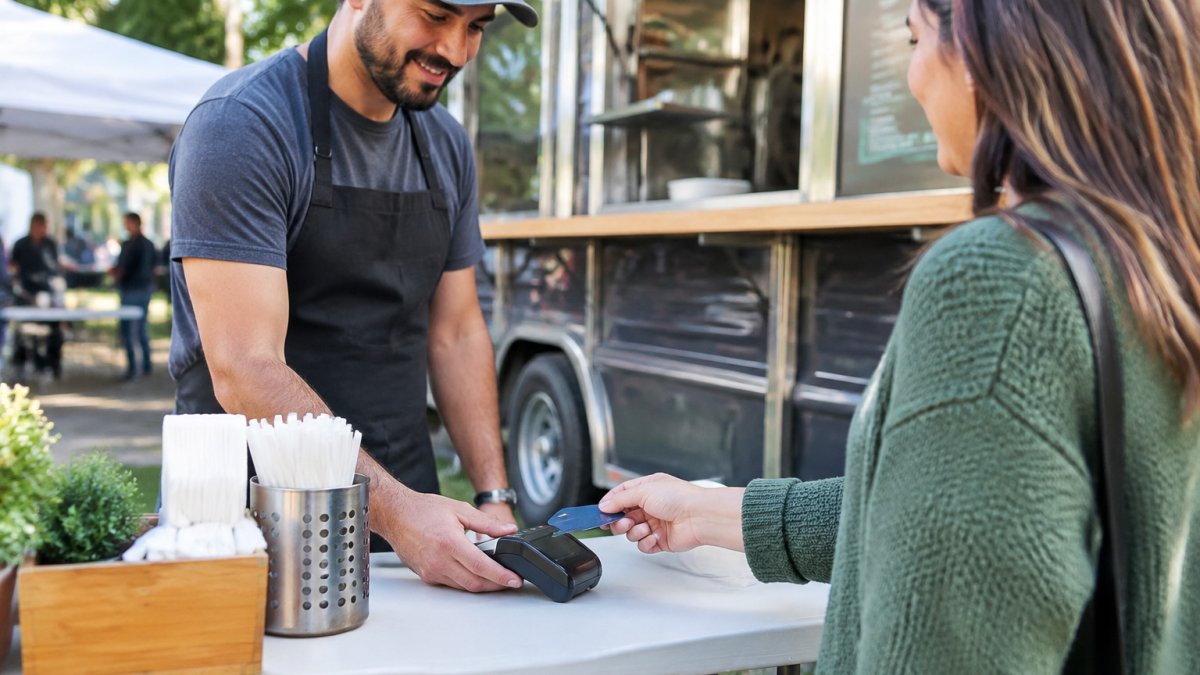
Look for options with no monthly minimum, portable hardware that runs on battery and works without a fixed internet connection, and simple pricing per transaction. Test how the terminal behaves when the network signal is weak, since outdoor events often have poor connectivity. If a provider cannot explain its offline behavior clearly, ask for a demonstration before you buy.
Offline Mode and Connectivity Failure
Offline mode, where a terminal stores transactions when it cannot reach the processor, varies by provider. The details matter more than the feature name:
- Storage limits. Terminals hold a limited number of offline transactions. Ask each provider for its exact limit.
- Amount caps. Some providers cap the dollar amount per offline transaction or per day. Ask whether any cap applies.
- Risk window. Offline transactions are not authorized in real time. If the card is declined when the batch finally reaches the processor, the sale can be reversed and you may not recover the goods or service.
- Settlement timing. Offline transactions usually settle later than online ones, which can affect cash flow at a multi-day event.
Decide your own offline cap before the event, not at the register.
Watch out: Confirm with your provider what happens if an offline transaction is later declined.
Hardware That Fits Event Selling
For occasional sellers, the hardware choice often matters more than the rate:
- Battery life. Look for a reader rated for a full day of selling, and carry a power bank for multi-day events.
- Cellular or Wi-Fi. A terminal with its own cellular connection reduces dependence on venue Wi-Fi, which is often overloaded.
- Tap-to-pay on a phone. Some providers let you accept contactless cards directly on a phone, which avoids a separate reader for very low volume.
- Receipt options. Text and email receipts avoid paper and printer costs at events.
Pricing for Infrequent Sellers
For a seller with modest monthly sales, a fixed monthly fee can be a large share of total cost. Run the numbers at your own volume before choosing a provider.
Also confirm whether the provider requires a contract or minimum monthly volume. Ask in writing before you sign.
PCI DSS Compliance and Offline Mode: What to Check Before You Switch
The Payment Card Industry Data Security Standard (PCI DSS) sets security requirements for any business that handles card data (PCI Security Standards Council). Many small businesses meet their obligations by using validated payment terminals and completing a self-assessment questionnaire. The exact requirements depend on how you accept cards, so confirm your level with your provider or a qualified adviser.
Before you switch, ask each provider:
- Is your terminal or system PCI-validated, and can you share the current listing?
- Who is responsible for which parts of compliance: the provider, or your business?
- What happens to transactions during a connectivity outage, and when do they settle?
- Is there an offline mode, and what are its limits on amount and storage time?
Clear answers to these questions protect you from surprises during an outage, which is when many owners first discover how their system really behaves.
Your Next Step: Compare Quotes Using Your Last 12 Months of Statements
The most useful comparison uses your own numbers. Gather your last 12 months of processing statements and note your total card volume, average ticket size, number of transactions, and every fee you currently pay. Then request written quotes from the alternatives you shortlist, using the same volume figures for each.
Compare the all-in annual cost, the switching timeline, and what support looks like outside business hours. Local Credit Card Processing can help you review those figures and explain the switching steps. Visit the Local Credit Card Processing website for current pricing and to learn about its free trial.
Frequently Asked Questions
What are the best payment processors for small businesses?
The best fit depends on sales volume, card mix and whether you sell in person or online. Higher-volume shops may compare flat-rate and interchange-plus pricing across providers. Ask each provider for a quote built from your last 12 months of statements, then compare effective rates rather than headline rates. Check contract length and early termination fees before signing anything.
What are third-party payment processors and how do they differ from merchant accounts?
Third-party payment processors, often called payment aggregators, let you accept cards under their shared merchant account. You can usually start the same day with little paperwork. A dedicated merchant account is opened in your business’s name with an acquiring bank, which typically means more underwriting but often lower rates at higher volumes and more control over holds and reserves. Aggregators are simpler for low-volume sellers, while merchant accounts often make sense once monthly card sales are consistently high.
How can I reduce credit card processing fees for my small business?
Start by reviewing your monthly statements to see the effective rate you actually pay, including monthly fees, PCI fees and per-transaction charges. Ask whether your provider uses interchange-plus pricing, which passes through the card network cost plus a fixed markup, instead of a flat rate. Accept debit and contactless payments where possible, since they often carry lower costs. Avoid long contracts with cancellation fees, and renegotiate once your monthly card volume grows.
What is PCI DSS compliance and do small businesses need it?
PCI DSS is the Payment Card Industry Data Security Standard, a set of security requirements set by the card networks for any business that stores, processes or transmits cardholder data. Nearly every business that accepts cards must meet it, though the required steps depend on how you take payments. Your processor can tell you which Self-Assessment Questionnaire applies to your setup.

Recent Comments