Table of Contents
- How Small Business Payment Processing Actually Works
- Small Business Credit Card Processing Fees Explained
- How to Choose a Payment Processor for Small Business
- Picking the Right Small Business Card Reader
- How to Accept Payments for a Small Business: Step-by-Step
- The Hidden Costs of Switching Payment Processors
- Frequently Asked Questions
Last Updated: October 7, 2026
How Small Business Payment Processing Actually Works
Small business payment processing moves money from a customer’s card to your bank account, usually within one to two business days.
Here is what happens when a customer taps a card:
- The card reader sends an authorization request to the processor
- The processor routes it through the card network to the issuing bank
- The bank approves or declines, and funds are held
- At day’s end, the processor batches transactions and settles them
- Funds land in your account, minus fees
Authorization takes seconds; settlement takes longer. That gap trips up new owners who expect money the same day.
Two terms matter: authorization reserves funds, and capture claims them. Most retail setups do both at once; restaurants and hotels often authorize first and capture later, once the final total is known.
Ask your processor about settlement time before you sign. A processor that funds next-day versus one that funds in three days makes a real difference to your cash flow, especially in your first year.
Small Business Credit Card Processing Fees Explained
Small business credit card processing fees break into three parts: interchange, assessments, and your processor’s markup. Interchange goes to the card-issuing bank.
That explains most of the frustration owners feel: two-thirds of your cost is set by banks and networks, not the company you sign with.
According to the Federal Reserve’s Regulation II debit card interchange standards, debit interchange is capped for large banks, which is why debit often costs less than credit.
The main fee types you will see:
- Transaction fees: a flat amount per swipe, tap, or keyed entry
- Percentage fees: a cut of each sale
- Monthly fees: account, statement, or gateway charges
- Incidental fees: batch fees, PCI fees, chargeback fees
Keyed-in transactions cost more than tapped cards because they carry higher fraud risk, real risk pricing from the networks, not a processor trick.
Why Two Businesses Pay Different Rates on the Same Volume
Two businesses can run identical monthly volume and still see very different effective rates. The difference comes from four variables:
- Card mix: rewards and premium cards carry higher interchange than basic credit or debit
- Channel: card-present taps cost less than card-not-present keyed or online entries
- Average ticket: a $5 sale and a $500 sale can carry the same flat per-transaction fee, so the small ticket pays a much higher percentage
- Industry risk: some categories carry higher interchange and stricter underwriting
A high-ticket, rewards-heavy business often pays a higher effective rate than a low-ticket, debit-heavy one, even at the same markup. Comparing quotes on one blended rate tells you almost nothing.
How to Read a Processing Statement
Your monthly statement is where the real cost lives. Check these line items:
- Effective rate: total fees divided by total volume. Calculate it yourself; do not trust the headline rate.
- Per-transaction fees: count them. A high per-transaction fee punishes small tickets.
- Batch and settlement fees: daily batch fees add up fast over a year.
- PCI and compliance fees: often a flat monthly charge, sometimes annual.
- Chargeback fees: typically a flat amount per disputed transaction, plus the lost sale.
If your statement does not itemize interchange separately from markup, you cannot verify your rate, which is the point of a bundled or tiered statement.
Interchange-Plus vs. Flat-Rate Pricing: Which Saves More?
Interchange-plus pricing passes through the actual interchange rate plus a fixed markup. Flat-rate pricing charges one percentage for everything, usually with a per-transaction fee on top. Which saves more depends on your average ticket and card mix: higher tickets and more rewards cards favor interchange-plus, while low volume and simple needs favor flat-rate for predictability.
| Pricing Model | How It Works | Best For |
|---|---|---|
| Interchange-plus | Cost + fixed markup per transaction | Higher volume, higher tickets |
| Flat-rate | One percentage across all cards | Low volume, simple needs |
| Tiered | Rates grouped into buckets | Rarely the cheapest option |
Avoid the tiered model: it hides real cost inside categories you cannot verify. If a provider will not show you interchange-plus, ask why.
Run your own effective-rate math before you sign. Take last month’s total fees, divide by total volume, and write the number down. That single figure is the only fair way to compare two quotes, and the only number a processor cannot dress up.
How to Choose a Payment Processor for Small Business
Choosing a payment processor for small business comes down to five checks: total cost, contract terms, support, hardware fit, and integration with your existing systems.
- Total cost: compare quotes on the same monthly volume and card mix
- Contract length: month-to-month beats a multi-year lock-in
- Support: ask how to reach a human at 6 PM on a Friday, then test it
- Hardware: confirm the reader works with your POS or accounting software
- Exit terms: read the early termination fee before you sign
That last point matters more than most owners expect: a low rate means nothing if leaving costs several months of fees.
The Contract Terms That Actually Cost You Money
Most guides say read the contract; few say what to look for. These clauses decide whether you are free to leave or stuck:
- Early termination fee (ETF): often expressed as a flat dollar amount or as a multiple of your average monthly processing. A flat fee is easier to swallow; a multiple can run into thousands if your volume grows.
- Liquidated damages clause: some contracts charge the remaining months of fees if you cancel. This is the most expensive exit term and the one to negotiate hardest.
- Auto-renewal: a one-year term that auto-renews for another year unless you give notice 30 to 90 days out. Calendar the notice window the day you sign.
- Rate-lock language: confirm whether your markup is locked or whether the processor can raise it mid-term. A locked markup with a capped increase is worth more than a slightly lower starting rate.
- PCI compliance fees: check whether the fee is flat or variable, and whether it is charged monthly or annually.
A practical tactic: get the contract in writing before you commit, and ask what it costs to cancel in month three versus month eighteen. The answer tells you how confident the provider is in keeping you.
Merchant Account vs. Payment Aggregator: What’s the Difference?
A merchant account is a dedicated account that lets you accept card payments directly, with your own rates and contract. A payment aggregator pools many businesses under one master account, trading control for simpler onboarding.
Merchant accounts win on cost at scale and give you a real underwriter relationship; aggregators win on speed for very small operations. If you process steady volume and want transparent pricing, a merchant account is generally the better long-term choice.
How to Switch Processors Without Getting Burned
Switching is where the real money hides, and most guides skip it. The new rate sheet is only half the math. Plan for these costs:
- Early termination fee: read your current contract and get the exact number in writing
- Hardware: old readers may not work with the new system, so price replacements
- Integration: POS and accounting links may need rebuilding, which can mean paid setup time
- Retraining: staff need time to learn a new checkout, and mistakes during the changeover cost sales
- Downtime risk: a botched cutover on a busy day is the most expensive line item of all
Run the numbers as total cost of ownership, not headline rate.
According to the PCI Security Standards Council, any business that stores, processes, or transmits card data must meet PCI DSS requirements, so factor compliance into your switch plan.
Ask about migration support before you commit. A provider that handles data transfer and keeps you running through the cutover removes most of the downtime risk.
Signing a long-term contract with an early termination fee locks you into rates you cannot renegotiate. If your volume grows, you will pay more than you should until the term ends. Always ask for month-to-month terms first, and if you accept a term, calendar the auto-renewal notice window the day you sign.
Picking the Right Small Business Card Reader
The right small business card reader depends on where you take payments. A countertop terminal suits a fixed checkout. A mobile card reader suits markets, deliveries, and service calls.
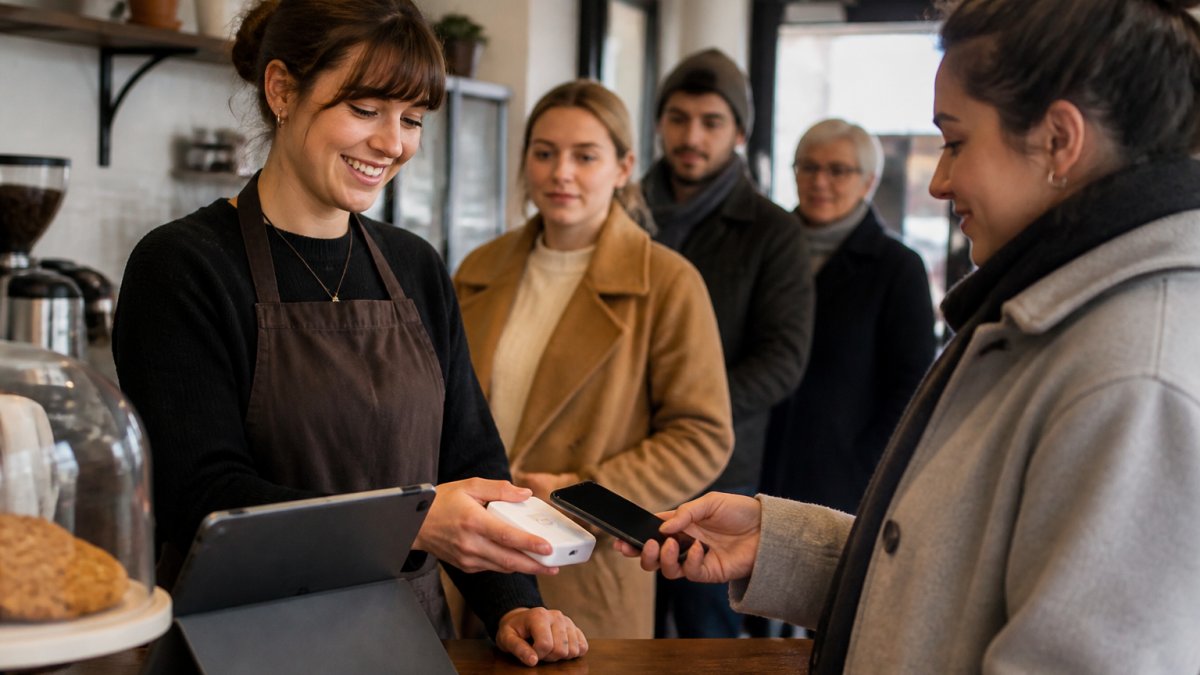
Match the hardware to the job:
- Countertop terminal: high-volume checkout, fast taps
- Mobile card reader: pop-ups, markets, field service
- POS-integrated reader: retail and restaurants needing inventory
- Virtual terminal: phone and mail orders
- Digital wallet acceptance: tap-to-pay from phones and watches
A reader that does not talk to your POS creates double entry and mistakes. Confirm compatibility before you buy, and ask whether the equipment is leased, bought, or provided at no upfront cost.
How to Accept Payments for a Small Business: Step-by-Step
Total Time: 3-7 business days
Difficulty: Beginner
What You’ll Need:
- Business registration and tax ID
- Bank account for settlements
- Average ticket and monthly volume estimate
- Existing POS or accounting software details
Expected Result: A complete application ready to submit.
Expected Result: Two or three quotes you can line up side by side.
Step 3: Apply and get approved [Time: 1-2 days]
Submit your application.
Expected Result: An active merchant account.
Expected Result: A working checkout that feeds your records automatically.
Step 5: Run a live test [Time: 30 minutes]
Process a small real transaction, then refund it.
Expected Result: Confidence that settlement and reporting work before your first busy day.
Expected Result: A checkout that runs without you standing at the counter.
Test with a real transaction before you go live. A refund test confirms both directions of the payment flow and catches setup errors while they are still cheap to fix.
The Hidden Costs of Switching Payment Processors
Switching payment processors costs more than the new rate sheet suggests. The real costs hide in contract exit terms, hardware replacement, integration work, and staff retraining.
- Early termination fees: often several months of processing
- Hardware: old readers may not work with the new system
- Integration: POS and accounting links may need rebuilding
- Retraining: staff need time to learn a new checkout
- Downtime risk: a botched cutover costs sales
According to the PCI Security Standards Council, any business that stores, processes, or transmits card data must meet PCI DSS requirements, so factor compliance into your switch plan.
Ask about migration support before you commit. A provider that handles data transfer and keeps you running through the cutover removes most of the downtime risk.
Switching processors or setting up payments for the first time should not cost you a week of downtime or a stack of hidden fees.
Frequently Asked Questions
How do small businesses accept payments?
Small businesses accept payments through a merchant account or payment aggregator that connects to a card reader, terminal, or online gateway. When a customer taps, dips, or swipes a card, the processor sends an authorization request to the card network, which approves or declines it. Funds typically settle in one to two business days for most processors, though some take up to five. You can accept payments in person with a countertop terminal or mobile card reader, online through a virtual terminal or payment gateway, or both through an omnichannel setup.
What is the average credit card processing fee for a small business?
Processing fees vary by provider and pricing model. Interchange-plus pricing passes through the card network’s interchange fee plus a small markup, while flat-rate pricing bundles everything into one percentage. Interchange fees are set by the card networks and vary by card type, so a rewards card costs more to process than a basic debit card. To compare offers accurately, ask each provider for a full fee schedule and calculate your effective rate on a typical month of transactions.
What should a small business compare when choosing a payment processor?
Compare the effective rate on your actual transaction mix, not the advertised headline rate. Ask about monthly fees, PCI compliance charges, batch processing costs, and early termination fees. Check settlement time and funding speed, since faster deposits help cash flow. Confirm whether the processor supports the payment types you need, including digital wallets, recurring billing, and online payments. Finally, ask about local technical support and what happens if hardware fails during business hours.
Can small businesses accept payments online and in person with one processor?
Yes. Most modern processors offer omnichannel payments, which means one merchant account handles in-person card readers, online payment gateways, and virtual terminals. This simplifies reconciliation because all transactions appear in one dashboard and settle to one bank account. If you sell online and in person, look for a processor with API integration and tokenization so stored card details work securely across both channels. Ask whether the same rate applies to card-present and card-not-present transactions, since online rates are usually higher.
Recent Comments